By Tekena Amieyeofori
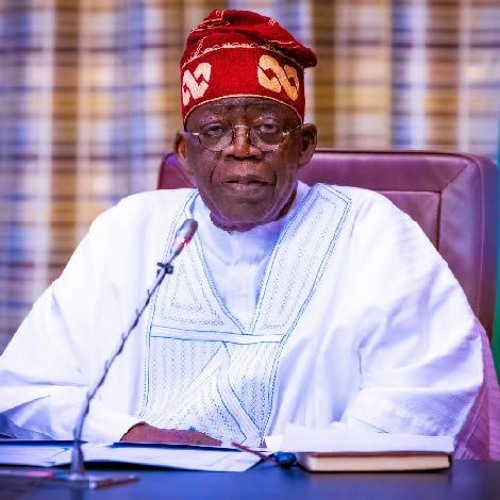
President Bola Ahmed Tinubu has given the green light to a new investment structure designed to unlock up to $50 billion in Nigeria’s deep offshore oil and gas sector and breathe life into major projects that have been stalled for years.
The new framework replaces the old model where companies had to negotiate fiscal terms individually for each project. In its place is a clear, rules-based system intended to draw in long-term capital to Nigeria’s deepwater operations.
Bayo Onanuga, the President’s spokesperson, announced in a statement on Tuesday evening that the approval also empowers the Nigerian National Petroleum Company (NNPC) Limited, the government’s designated party under production sharing contracts (PSCs), to begin the required amendments to qualifying PSCs to put the framework into effect.
Olu Verheijen, the President’s Special Adviser on Oil and Gas, said in the same statement that the reform is also meant to boost Nigerian involvement in the offshore segment.
“A defining feature of this reform is its emphasis on Nigerian industrial capability,” Verheijen said.
By setting out defined rules and incentives, the framework is expected to give investors more predictability and remove the need for case-by-case fiscal negotiations.
The move comes at a time when the government is pushing to ramp up oil output, attract new foreign investment, and restart key deepwater developments that have been held back by regulatory and commercial uncertainty.
Officials said the framework will make Nigeria more competitive as a destination for deepwater oil and gas funding, while also advancing local industrial growth.